18th November 2026
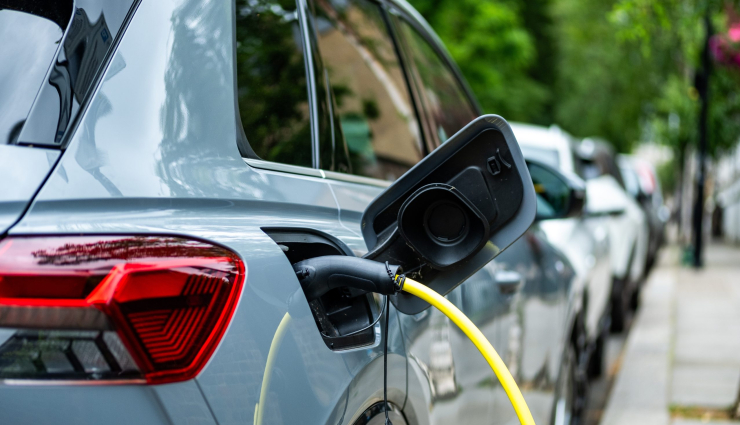
With fuel costs remaining a consideration for many businesses, switching to electric vehicles continues to be an attractive option. However, changes to the tax relief available on electric company cars mean that the timing of a purchase could soon become more important.
From April 2027, the current 100% first-year allowance for qualifying new electric cars is due to end, changing how quickly businesses can claim tax relief on their investment.
For businesses considering making the switch, understanding these changes now could help with financial planning.
The 100% first-year allowance allows businesses to deduct the full cost of a qualifying new electric car from their taxable profits in the year the expenditure is incurred.
For example, if a limited company purchases a qualifying new electric car for £40,000, it could potentially deduct the full £40,000 when calculating its taxable profits for that accounting period.
This does not mean the business receives £40,000 back in tax. Instead, the deduction reduces the profits on which tax is calculated, potentially providing a significant tax saving.
The relief is currently available for qualifying new and unused electric cars with zero CO₂ emissions.
The current allowance is scheduled to end on 31 March 2027 for Corporation Tax purposes and 5 April 2027 for Income Tax purposes.
From these dates, businesses purchasing qualifying electric cars will no longer be able to claim the full cost through the 100% first-year allowance.
Instead, tax relief will generally be available through writing-down allowances, which spread deductions over a number of years.
For electric cars with zero CO₂ emissions, the applicable writing-down allowance rate is set to be 12% annually on a reducing-balance basis from April 2027.
This means businesses will still be able to claim tax relief on qualifying expenditure, but it will take longer to receive the benefit.
The main difference is how quickly businesses can benefit from the available tax relief.
Under the current rules, qualifying businesses can deduct the full cost of a new electric car from their taxable profits in the year of purchase.
From April 2027, this relief will instead be spread over a number of years through writing-down allowances.
Although businesses will still be able to claim tax relief, receiving the benefit over a longer period could affect cash flow and financial planning.
For businesses already considering investing in electric vehicles, the timing of a purchase could therefore be an important consideration.
The changes are not limited to electric cars. The existing 100% first-year allowance for qualifying expenditure on electric vehicle charging points is also scheduled to end in April 2027.
Businesses installing charging facilities may still be eligible for other capital allowances, depending on the equipment and circumstances.
For those considering investing in electric vehicles and associated charging infrastructure, it may therefore be worth reviewing both elements together.
With the deadline approaching, businesses already considering purchasing an electric car may wish to review their plans.
However, purchasing a vehicle purely to secure tax relief may not always be the most appropriate decision.
The overall cost of the vehicle, financing arrangements, business use and wider tax implications should all be considered.
There are also differences between purchasing and leasing a vehicle, and additional tax considerations where an electric company car is made available for private use by a director or employee.
Taking advice before committing to a purchase can help ensure that the decision makes sense both financially and commercially.
Whether you’re considering purchasing your first electric company car or reviewing your existing business vehicles, understanding the tax implications can help you make an informed decision.
At Thompson Jenner, we can help you assess the capital allowances available, understand how the upcoming changes could affect your business and consider the wider tax implications of purchasing or leasing an electric vehicle.
If you’re planning to invest in an electric company car, get in touch with our team to discuss your options before the rules change in April 2027.